GBS ADVOCACY
Insurance Insights
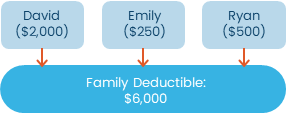
Annual Deductible
Individual: $2,000
Family: $6,000
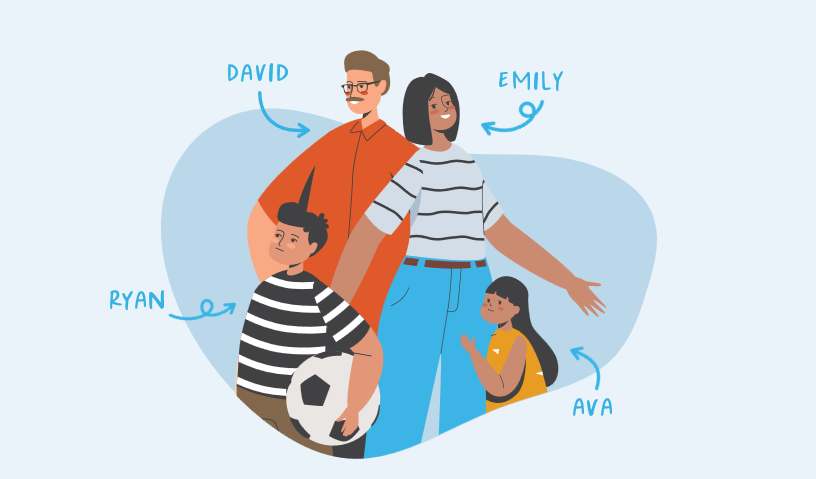
Medical Expenses
David: $2,000
Emily: $250
Ryan: $500
With a non-embedded family deductible, your family will be paying the deductible until the entire family deductible is collected.
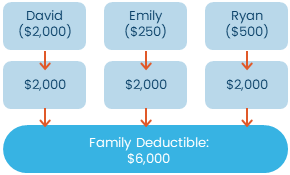
Annual Deductible
Individual: $2,000
Family: $6,000
Medical Expenses
David: $2,000
Emily: $250
Ryan: $500
With an embedded family deductible, the plan begins to make payments as soon as one member of the family has reached their individual deductible.
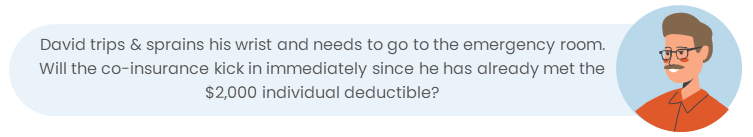
The family has only had a total of $2,750 in medical expenses. David will need to pay the remaining $3,250 of the family deductible before the co-insurance will take effect. Once the co-insurance is in effect, he will only need to pay 20% of the remaining emergency room expenses.
David only has to meet his individual deductible of $2,000 and he has already had $2,000 in medical expenses. David’s HDHP will help pay for this trip to the emergency room, and he is only subject to the co-insurance. However, if anyone else in the family had tripped instead of David, the co-insurance would not kick in for them until they hit their $2,000 individual deductible.
Our GBS team has the answer! Reach out to our experts today for more information on understanding deductibles, your health insurance plan, or other ways to succeed as a healthcare consumer. Let us provide the resources you need for you or your team.